A reported 35-year prison sentence arising from a Rs. 130 million fraud involving a chief teller raises questions about the systems intended to prevent financial misconduct. Criminal responsibility may rest with the individual convicted, but the public also deserves to understand how a fraud of such magnitude could occur within a regulated financial institution.
A chief teller has reportedly been sentenced to 35 years’ imprisonment in connection with a financial fraud involving approximately Rs. 130 million. The reported punishment is substantial, reflecting the seriousness with which the criminal justice system treats offences involving the misappropriation of money entrusted to financial institutions.
The precise terms of the sentence, including whether individual sentences are to run concurrently or consecutively, require confirmation from the court record. That distinction is important because the aggregate sentence announced in court does not necessarily represent the period an offender will actually serve.
Submit Your Press Release
Get your company news, announcements, launches, appointments and events in front of a wider audience.


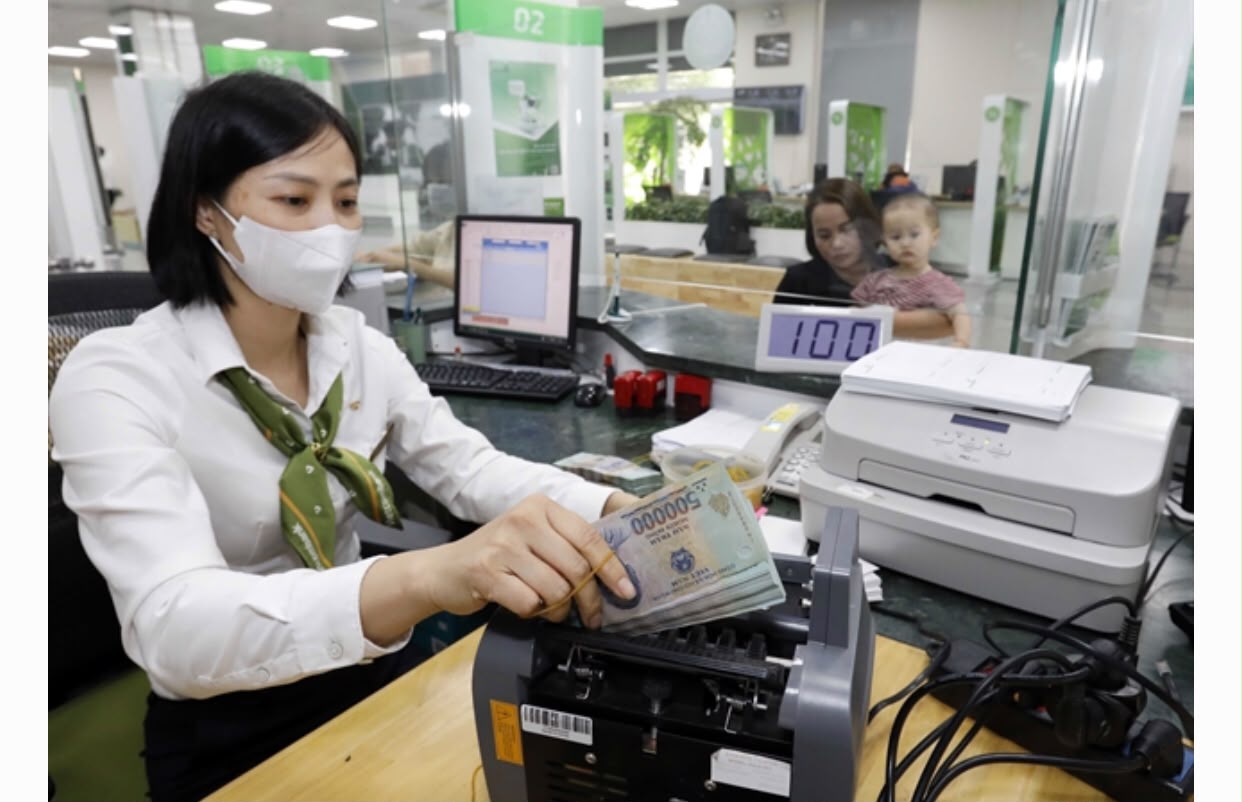
A chief teller occupies a position of considerable trust within a banking or financial institution. The role ordinarily involves responsibility for cash operations, transaction verification, balancing procedures and compliance with established financial controls.
These responsibilities exist within a broader system of supervision.
Financial institutions are not expected to depend exclusively upon the honesty of individual employees. They are required to maintain procedures designed to prevent errors, detect irregularities and identify suspicious transactions before losses become substantial.
Those procedures commonly include daily reconciliation, supervisory authorisation, transaction limits, independent verification, internal audits and restrictions on access to financial systems.
The purpose is straightforward.
No single employee should ordinarily be able to manipulate significant financial transactions indefinitely without generating discrepancies capable of being detected.
When a fraud involving Rs. 130 million reaches the criminal courts, it is therefore reasonable to ask what happened to those safeguards.
Was the misconduct committed through falsified documentation, unauthorised withdrawals, manipulation of accounting records or some other mechanism? Over what period did the losses accumulate? When were the irregularities first detected, and who identified them?
Were there earlier discrepancies that should have prompted investigation?
These questions are not intended to transfer criminal responsibility from the offender to colleagues or supervisors who may have acted entirely properly.
They concern institutional accountability.
A financial institution may successfully assist in the prosecution of an employee while still having important lessons to learn about the weaknesses that permitted the offence.
There is also the question of recovery.
A prison sentence punishes criminal conduct, but it does not automatically restore money lost through fraud. Where funds have been misappropriated, the institution and relevant authorities must determine whether assets can be traced, recovered or otherwise used to compensate those who suffered losses.
The distinction between punishment and restitution is particularly important where customer funds or public money are involved.
Sri Lanka’s financial sector depends upon confidence. Depositors must believe that the institutions holding their money operate reliable systems of supervision and control.
That confidence cannot rest simply upon the prospect that an employee who commits fraud will eventually be imprisoned.
It must rest upon reasonable assurance that fraud can be prevented, detected and contained.
The sentence also invites consideration of proportionality within the criminal justice system. Financial offences involving substantial sums can attract severe penalties, while other serious forms of misconduct may produce very different sentencing outcomes.
Comparisons require care because offences, statutory penalties and individual circumstances differ. But public confidence benefits when sentencing decisions are clearly explained and consistently applied.
There is a broader lesson in this case.
A conviction may bring an individual criminal proceeding to an end, but it should not necessarily bring institutional examination to an end.
If the financial system failed to identify the misconduct promptly, understanding that failure is essential to preventing repetition.
A bank’s responsibility is not discharged merely because the person responsible for a fraud has been punished.
The public is entitled to know whether the controls have been strengthened, whether the money has been recovered and whether the lessons of the case have been applied.
Thirty-five years is an extraordinary sentence.
But the measure of an effective financial system is not how severely it punishes fraud after the event. It is how successfully it prevents fraud from occurring in the first place.